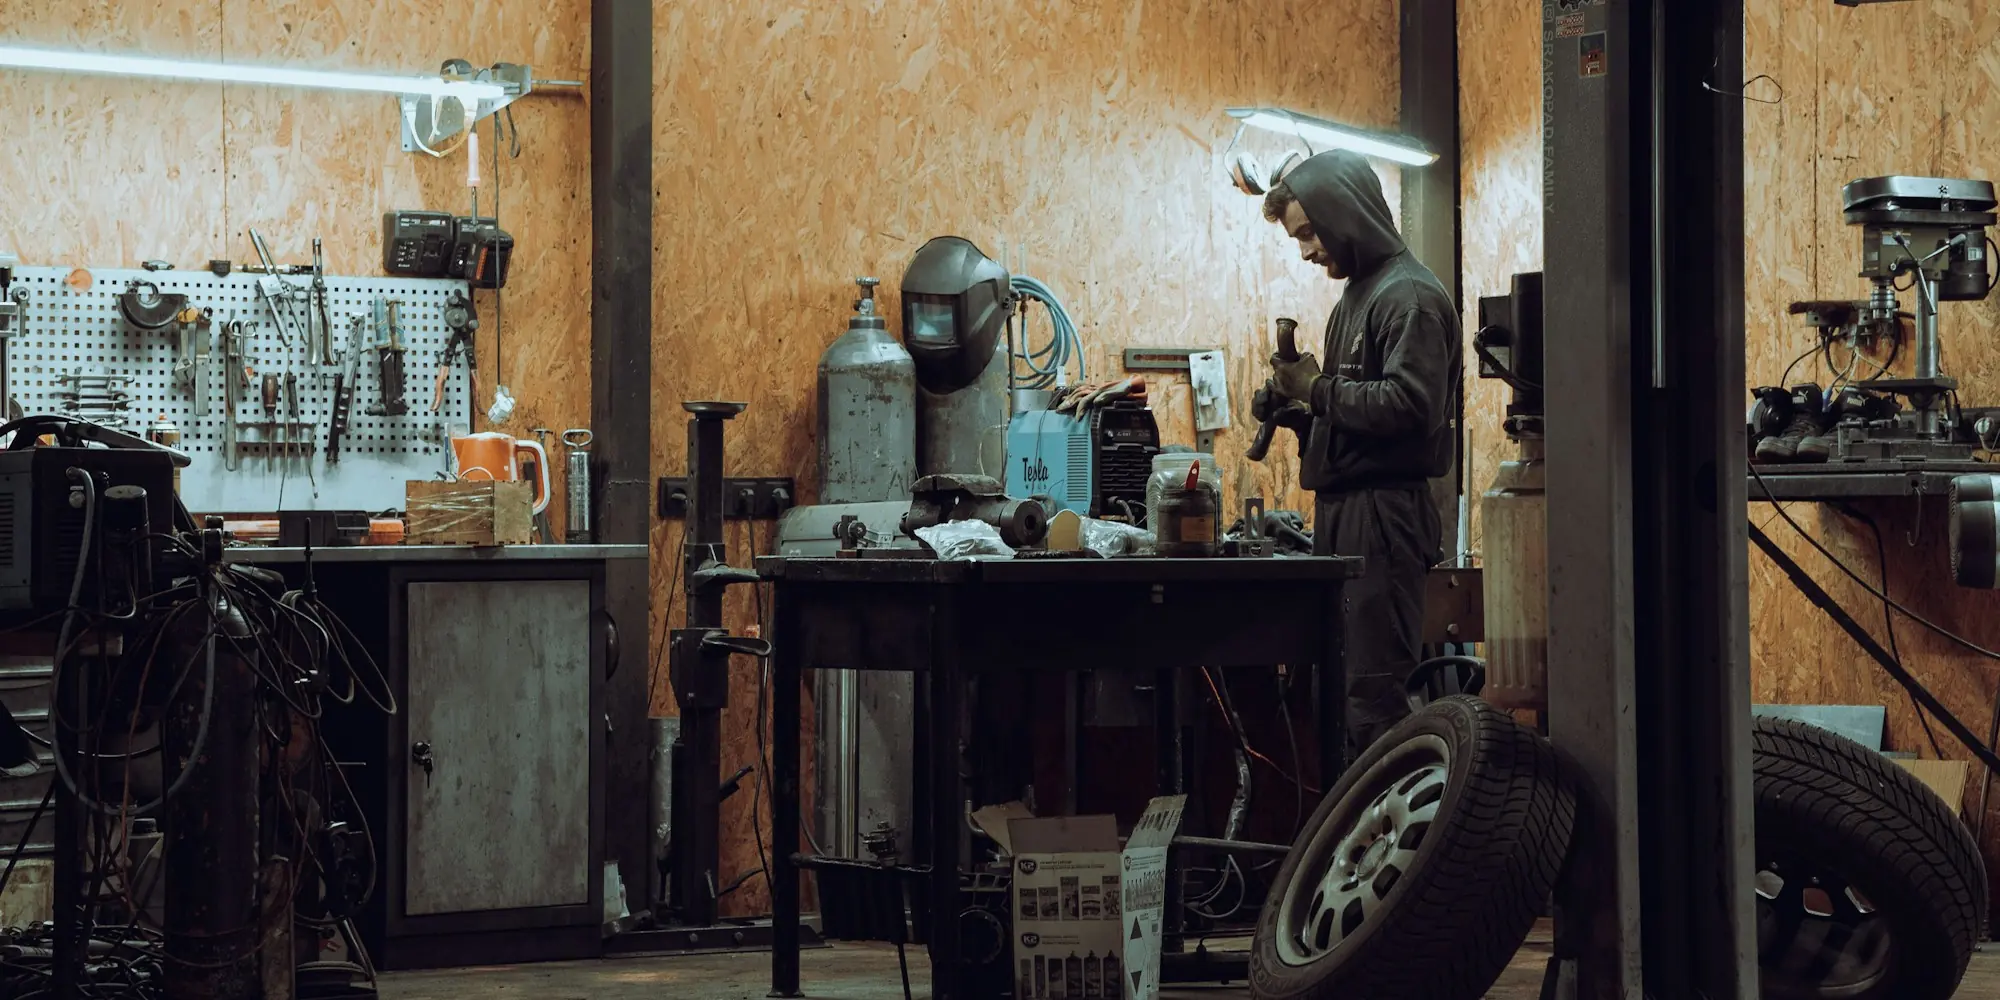
Most auto repair shops pay for equipment, parts, payroll and growth with four kinds of financing, and each one suits a different job. Equipment financing pays for a lift, an alignment system or a diagnostic platform, with the equipment itself as security. A line of credit covers parts orders and payroll while insurance claims and fleet accounts are still unpaid. Revenue-based financing, often called a merchant cash advance, covers a quick one-off need and is repaid as a share of the shop's deposits. SBA and bank loans pay for big, slow projects such as adding bays or buying a second shop, over terms measured in years. The right choice depends on how long the thing you are paying for will keep earning, and on how long your customers and insurers take to pay you.
Below, we cover why full bays can still leave a shop short, how each option works, and what funders look at. Our auto services funding page has a shorter overview.
Why repair shops run short of cash with the bays full
A repair starts with a parts order and a technician's hours. The supplier and the payroll are paid on their own schedule, the customer pays at pickup, and an insurer or a fleet account pays later still. Insurance work stretches that gap the furthest. In California, the state's fair claims settlement regulations give an insurer up to 40 calendar days after it receives proof of a claim to accept or deny it, and up to 30 more days after accepting it to pay. Those are outer limits, and other states set their own rules, but they show how long a shop can be left carrying a job it has already finished.
Take an example collision repair billed at $9,000. The shop buys $3,800 of parts in the first days, pays $2,400 of technician wages across two weekly payrolls and uses $700 of paint and materials. The owner pays a $1,000 deductible at pickup on day 14, and the insurer pays the remaining $8,000 on day 45. For a month the shop is out $5,900, and with ten such jobs open at once, about $59,000 of its cash is tied up in parts and wages no one has paid for yet. All of these figures are illustrative.
Most shops have little cushion for that. The Census Bureau's County Business Patterns for 2023 counted 169,572 automotive repair and maintenance establishments with paid employees, and about 60% of them had fewer than five employees. In the Federal Reserve's Small Business Credit Survey, published as the 2025 Report on Employer Firms, 51% of employer firms across all industries named uneven cash flow as a financial challenge, a category the survey says includes collecting on receivables.
The main ways to finance an auto repair shop
Equipment financing for lifts, alignment and diagnostic systems
Equipment financing pays for a specific piece of equipment and uses that equipment as security. In a shop, that means lifts, alignment racks, diagnostic platforms, calibration rigs for driver-assistance systems, tire changers, frame machines and paint booths. Offers usually come back within one to two business days, and because the funder can recover the equipment, approval tends to be easier than for unsecured credit. In the Fed survey, 68% of applicants for auto or equipment loans were fully approved, the highest share of any product it lists, compared with 47% for business lines of credit and 33% for merchant cash advances.
The useful test is whether the equipment pays its own way. Suppose a new alignment system lets an example shop sell eight more alignments a week at $120 each. That is about $4,160 a month, so as long as the monthly payment sits well below that figure, the rack covers itself from its own work. The same arithmetic works for a second lift or a scan platform that keeps electrical work in house. Our equipment financing page lists what it covers, and our guide to how equipment financing works goes through leases, down payments and used equipment.
A line of credit for parts and payroll between payments
A line of credit gives you a limit, up to $250,000 through our network, and you draw only what you need. You repay what you drew weekly or monthly, and the room opens up again as you repay. A line fits the insurance gap closely, because you draw for parts and payroll and pay it down when the claim or fleet payment clears. In the example with ten open jobs, a line near $60,000 would carry the shop through the wait. Our line of credit page explains limits, draws and repayment.
Revenue-based financing, or a merchant cash advance
With revenue-based financing, a funder buys a share of your future sales at a discount. It pays you a lump sum now and collects a larger fixed total, usually by daily or weekly debit from your business account, until that total has been collected. Advances arranged through us range from $5,000 to $2,000,000, typically fund in one to two business days, and usually need no collateral. They are priced with a factor rate, so as an example, a factor rate of 1.30 on a $30,000 advance means $39,000 paid back in total.
An advance fits a short need with a clear payoff, such as a compressor that failed on a Monday, and its price adds up over a project that takes years to pay back. Our revenue-based financing page covers amounts, timing and fit.
SBA and bank loans for more bays or a second shop
SBA and bank loans take weeks and ask for tax returns, a personal financial statement and a schedule of your existing debts, and in exchange they offer the longest terms. The SBA's 7(a) program lends up to $5 million, and its listed uses include working capital, equipment, real estate and changes of ownership, which covers buying an existing shop. The 504 program provides long-term, fixed-rate financing of up to $5 million, or $5.5 million for some projects, for buildings, land and machinery with at least 10 years of remaining useful life, and it cannot be used for working capital or inventory. These suit adding bays or buying a second location, though only 32% of SBA loan applicants in the Fed survey were fully approved. Our SBA and bank loans page lists what lenders ask for.
Body shop, tire shop and car wash financing
Body shops tend to carry the longest waits, because so much of their work is paid by insurers. The Bureau of Labor Statistics counted about 163,200 automotive body repairer jobs in 2025, 60% of them in body, paint, interior and glass repair shops. Their equipment is expensive and specific (a paint booth, a frame machine, measuring systems), so equipment financing is the usual starting point, with a line of credit beside it for the weeks between finishing a car and receiving the insurer's check.
Tire shops buy stock ahead of the season that sells it, such as winter tires ordered before the first cold weeks, and a line of credit suits that pattern because you draw for the order and repay as the tires sell. Car wash financing usually splits in two, with the tunnel equipment, dryers and pay stations financed as equipment and the land and building suited to an SBA 504 or 7(a) loan.
Some shops with large fleet accounts sell those invoices to a factoring company to be paid sooner. Invoice factoring is offered by specialist firms and we do not arrange it, and the same goes for floor plan financing on cars held for sale.
Hiring technicians before the work pays for them
The BLS counted about 825,800 automotive service technician and mechanic jobs in 2025, a quarter of them at mechanical and electrical repair shops, and it projects about 66,200 openings a year from 2025 to 2035, many of them to replace workers who leave the trade or retire. Median pay for the job was $50,620 in 2025. A new hire is paid from the first Friday but often takes weeks to bill a full schedule, and at the median wage, eight weeks of pay comes to about $7,800 before benefits (an illustrative figure). That short, predictable cost suits a line of credit better than a long loan.
What funders look at, including auto repair funding with bad credit
Every funder sets its own thresholds. Revenue-based funders build most of their decision from your last four months of business bank statements, looking at monthly deposits and how steady they are, how often the balance runs low, and what other debits already come out of the account. A shop whose insurance checks arrive in lumps will show uneven deposits, so explain that pattern when you apply.
How the business is described matters as well. In our experience, funders like the repair trade for its steady demand and repeat customers, while many treat auto sales as a different and riskier business. If your shop also sells a few cars, say how much of your revenue comes from service, so the file reads as the service business it is. The Auto Care Association ties the trade's growth to drivers keeping their cars longer, reporting that U.S. vehicles were averaging over 12.8 years on the road and that light-duty aftermarket sales grew 5.7% in 2024 to $413.7 billion.
Time in business counts too. In the Fed survey, 48% of applicants with five years or less in business were fully approved, compared with 64% of firms open 21 years or more. If your credit is weak, a low score narrows the list of funders rather than ending the search. Most funders prequalify from bank statements and a soft credit pull, steady deposits carry real weight with revenue-based funders, and equipment financing is often the easier path because the equipment secures it. Our guide to qualifying for a merchant cash advance goes through the requirements.
What auto shops use financing for
In the Fed survey, 56% of applicants across all industries sought financing to meet operating expenses and 27% to make repairs or replace capital assets. In a repair shop, those turn into a short list of familiar requests.
| Need | What tends to fit | Why |
|---|---|---|
| A lift or compressor that fails mid-week | Equipment financing, or a short advance if it cannot wait | The shop loses a bay's income every day the equipment is down. |
| An alignment system or diagnostic platform | Equipment financing | The equipment secures the financing and earns its payment from new work. |
| Parts and payroll while insurance claims are open | A line of credit | You draw as the work starts and repay as each claim pays. |
| Seasonal tire stock or a bulk parts buy | A line of credit or a short revenue-based advance | The cost pays itself back as the stock sells. |
| Hiring and training a technician | A line of credit | The cost ends once the new hire bills full hours. |
| Adding bays or buying a second shop | An SBA 7(a) or 504 loan, with equipment financing for the new bays | The project earns for years, so a long term keeps the payment in line with what it brings in. |
Mistakes that cost auto shops the most
The most expensive mistake we see is paying for a long-term project with a short advance. New bays or a second location keep earning for years, while an advance is usually repaid within months, so the payments come out of current work long before the project has paid for itself. If it can wait the few weeks an SBA or bank loan takes, the payment will be smaller.
The second is stacking, which means taking a second or third advance while the first is still being repaid. Each one adds another debit to the same account, often a daily one, and for a body shop waiting on several insurance checks that can drain the account in its lightest weeks. Consolidation replaces several advances with one weekly or monthly payment on a longer term, though the total cost may not go down, as our post on MCA consolidation explains.
The third is signing the first offer without comparing it. Offers on the same file differ in payback, payment frequency and early payoff terms, and with lumpy insurance deposits a weekly payment can leave more room than a slightly cheaper daily one.
How to apply for auto repair shop financing
- Fill out the short application with your monthly revenue, time in business and what the money is for. There is nothing to pay to apply or to see offers, and no obligation to accept one.
- Add your last four months of business bank statements, by uploading them or connecting your bank read-only. For an SBA or bank loan, have tax returns, a personal financial statement and a list of current debts ready too.
- We send your file to funders in our network that fund repair and body shops, bring their offers back side by side, and go through the payback, payment and early payoff terms with you before anything is signed.
- Most applicants are funded within one to two business days of choosing an offer, and some the same day. SBA and bank loans take several weeks.
A new lift and a stack of open insurance claims call for different products, so say what the money is for. Our page for repair and body shops sums up what tends to fit, and to talk it through first, call us at (818) 351-0225.
Questions auto shop owners ask about financing
Can an auto repair shop get financing with bad credit?
Many can, though with fewer options, because revenue-based funders lean on bank statements and equipment financing is secured by the equipment, so a low score narrows the list of funders rather than ending the search.
How do you finance auto shop equipment?
Most shops use equipment financing, which uses the lift, alignment rack or diagnostic system as security and usually produces offers within one to two business days, while long-life purchases may fit an SBA 504 loan.
Can I get a loan to buy an existing auto repair shop?
Buying a shop is usually financed with an SBA 7(a) loan, whose listed uses include changes of ownership, and because the lender asks for tax returns, a personal financial statement and a debt schedule, expect the process to take several weeks.
How can a body shop cover costs while waiting on insurance payments?
A line of credit is the usual fit, since you draw for parts and payroll as the repair starts and repay when the insurer's payment clears.
Does applying for auto shop financing hurt my credit score?
Getting matched with funders does not need a hard credit pull, since most funders prequalify from bank statements and a soft pull, and if a funder runs a hard pull in final underwriting, you will know before it does.
